 Impact
Lending to community housing providers in Victoria
Community housing providers are among the largest borrowers in our loan book, and Victoria is where a growing share of that lending is going.
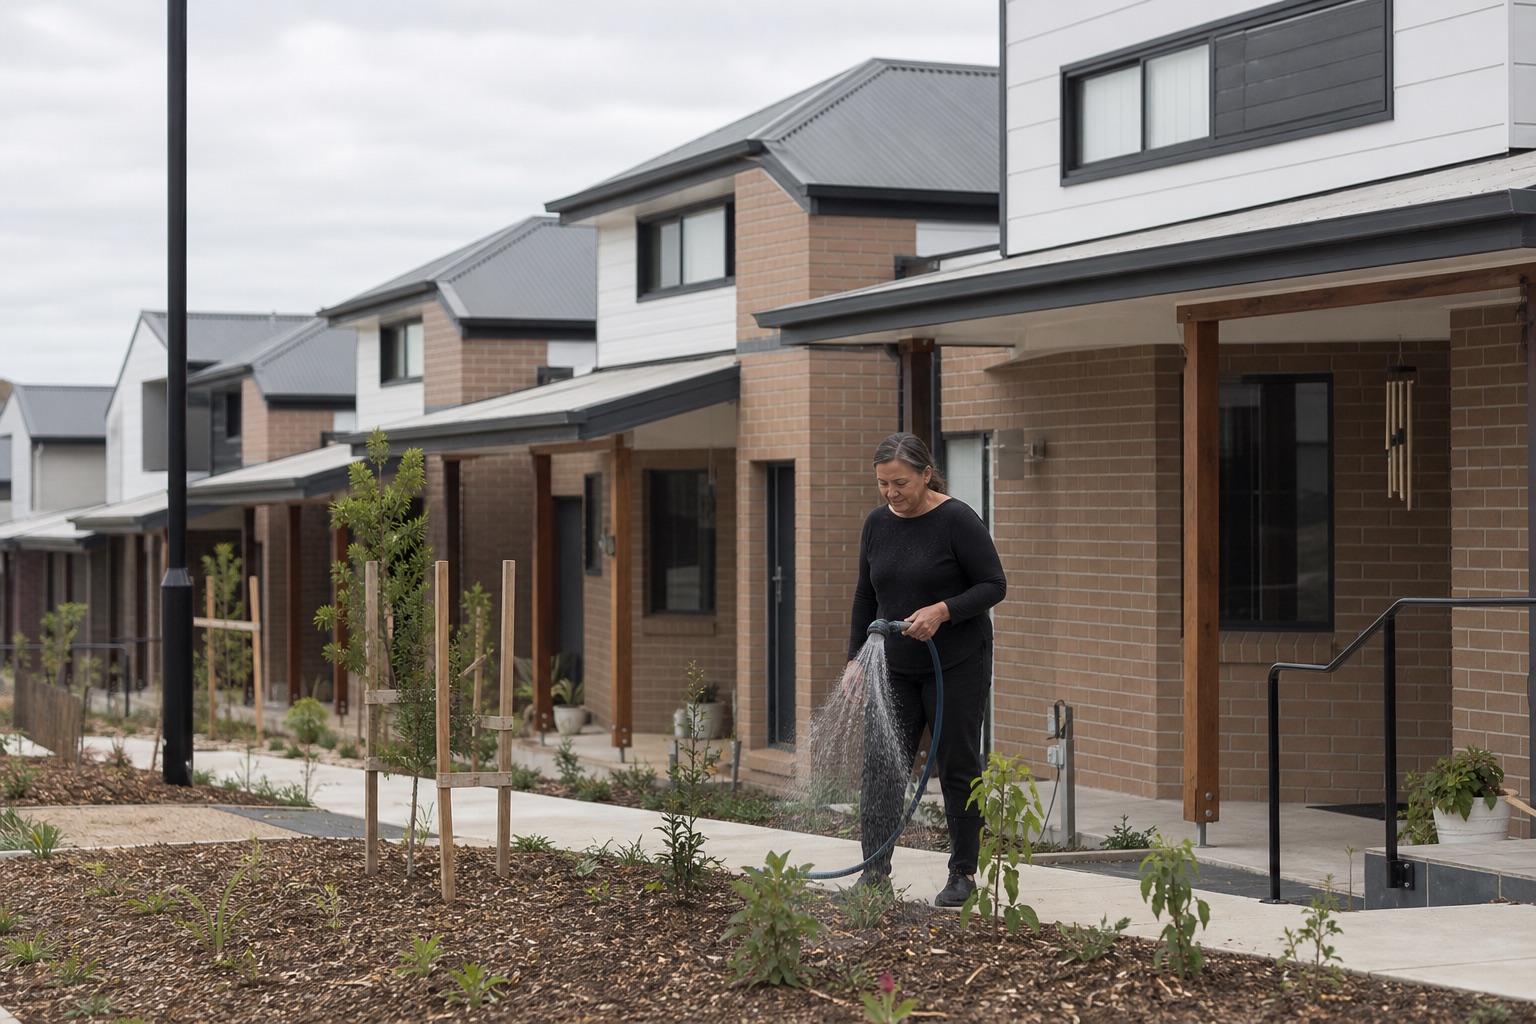
Community housing providers are among the largest borrowers in our loan book, and a growing share of that lending is going to Victoria. Registered providers there are acquiring and building homes at a pace that their own reserves cannot fund alone, and bank debt is the difference between a project starting this year and starting in five.
The organisations we lend to are registered housing agencies and not-for-profits with long-term tenancies, government-backed income and a development pipeline they can evidence. What they need from a lender is straightforward: debt written over a term that matches the life of the asset, and an assessor who understands that rental income from social housing behaves differently from income at market rents.
That understanding is the whole point of a bank like this one. A provider's income is capped by design, its tenants are by definition the people least able to absorb a rent rise, and its assets are homes it has no intention of selling. A lender that prices and structures as though it were dealing with a developer will get the answer wrong.
The lending funds acquisition of existing stock, new construction, refurbishment of homes that have fallen below standard, and refinancing of facilities that no longer suit. It sits inside Charity Loans, and where a project also improves the energy performance of the homes it can be paired with the Energy Efficiency Programme in our Green Loans — which matters most to tenants, who pay the power bills.
Victoria is not the only state where this is happening, but it is where the pipeline is currently deepest, and we expect community housing to remain the largest single sector in our book for some time.
All lending is subject to eligibility, assessment and approval by Charity Bank Australia, and security may be required. Nothing in this article constitutes an invitation to engage in investment activity nor is it advice or a recommendation, and professional advice should be taken before any course of action is pursued.
For one provider's account of what a loan made possible, read the Yarra Valley Community Housing story.
About Charity Bank Australia
Charity Bank Australia is the loans and savings bank owned by and committed to supporting the social sector. We use our savers’ money to make loans to housing, education, social care, community and other social purpose organisations — over 1,480 loans and A$653 million lent so far.
Nothing in this article constitutes an invitation to engage in investment activity nor is it advice or a recommendation and professional advice should be taken before any course of action is pursued.
 Online Banking
 Savings